… in 30 years time, you look back and realise you could have been substantially more financially secure and well-off (picture a broke, stressed older person), except when you were in your twenties you didn’t do one simple thing because you had a party to go to, or a friend to catch up with or decided it was a nice day to go for a drive…
And that one thing you didn’t do became yet another thing later that you ignored or meant to get around to but didn’t, and then that happened again, and again and again and the years rolled by as you gave priority to potentially less important things, and yet ‘getting things sorted’ could have been less than an hour of your time at the time…
And now you’re in your fifties, what would you go back and say to yourself (or your questionably highly-intelligent children)?
One thing I have learned in many years of finance far above any investment principal or ‘clever strategy’ is that just like interest and earnings can compound, so too can bad choices, errors or perhaps most insidiously & fatally, simply a lack of action – all which compound as repeated and major detrimental impacts on a person’s situation.
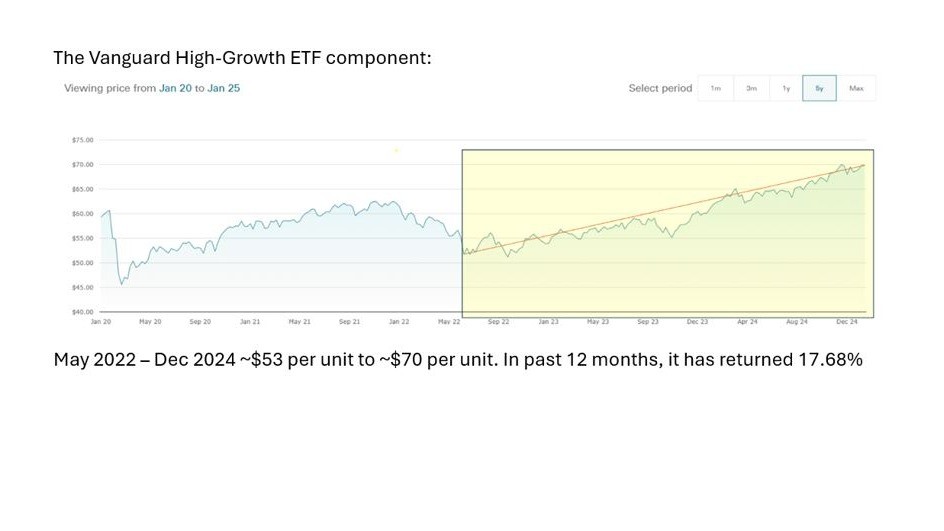
Back in June 2022 we initiated a small Vanguard investment for you each, part cash, part High-Growth ETF.
The Vanguard High-Growth ETF component:
-
May 2022 – Dec 2024 ~$53 per unit to ~$70 per unit.
- In past 12 months, it has returned 17.68%
The initial ~$4,500 has grown to ~$5,735 and while it may not look spectacular, bear in mind that over 43% of the total is just sitting in cash, awaiting your attention and placement.
To put it in context, add some zeroes on the end and if you had an investment that went from $450,000 to $573,500 in 2.5 years with a huge amount of it sitting in low-risk cash with no going-to-work-effort on your behalf, you would be pretty happy. Now imagine if almost half of it wasn’t languishing in cash over that time…
Bringing it back to reality, as mentioned and recommended at the time, imagine if you had not only considered where you wanted to put that cash component yourselves but also started up the regular $200/month (that you wouldn’t have missed) over the last 2.5 years, or 30 months for $6,000 of your own funds. The figure would be well over $13,000 by now… again it may not sound spectacular but compared to getting between 0 – 4.5% like any (excess) savings has for the past period, it leaves it for dead.
With no extra work hours or physical effort on your behalf, except the initial log-in, set up the auto-invest to your bank account which probably would take 15 mins tops if you’re organised.
So again, picture that older broke person… the type that just does the things ‘they want to do’ without any conscious plan or effort or thought to the future, even in the small things like direction or placement of money.
Life balance, enjoying nature, being spiritual or ‘at peace’ and ‘being kind to yourself’ are all important – but so too is simple common sense and ensuring you set up good habits and take easy simple steps to become fiscally responsible and secure.
A great (Henry David Thoreau) quote that I love: “If you have built castles in the air, your work need not be lost; that is where they should be. Now put the foundations under them.”
Making money isn’t that hard. Keeping it and getting it to do the work for you is simply a change of mindset and putting sensible choices first, regardless of how much income you actually earn – I have met many, many broke people who earned millions in personal income over their life but were too loose with it, but also many people who are very comfortably retired millionaires but earned average wages or less throughout their lifetime.
The difference was the price – they simply paid attention and spent time.
‘Money doesn’t respect those who don’t respect it’ is not just a figure of speech; it is a reality I have witnessed first-hand repeatedly throughout my career.
Spend at least 30 minutes at least once a year to make sure you’re doing the right things financially – the 50 year old version of you will greatly appreciate it (as will the 30, 35, 40, 45 year old versions).
Love Dad